


In June 1989, former Treasurer Paul Keating quipped “I guarantee if you walk into any pet shop in Australia, what the resident galah will be talking about is microeconomic policy.”
Today those galahs are likely talking about Australia’s productivity growth slowdown, which has dominated the economic discussion for many months.
Productivity measures how much the economy produces for each hour worked. When productivity rises, businesses can produce more without people necessarily working longer hours, supporting higher wages, economic growth and living standards. When productivity slows, those gains become harder to achieve.
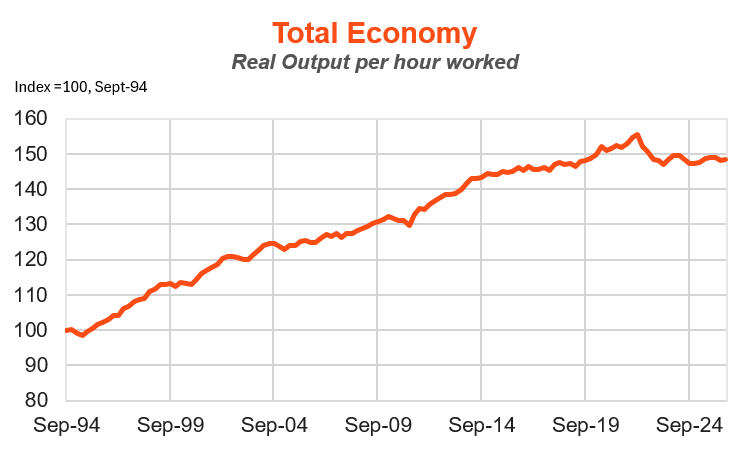
In Australia, the slowdown has been particularly pronounced. In the decade to June 2026, labour productivity growth – the amount of goods and services produced for each hour worked – averaged just 0.2% a year. That compares with annualised growth of 1.6% and 2.0% in the previous two 10-year periods.
The slowdown in productivity is apparent in the chart below. Exactly why productivity growth has slowed so notably, and what might be done about it, is the subject of this article.
Source: Betashares, ABS
What accounts for the slowdown?
There are two broad reasons why national productivity can change. Productivity can rise or fall within individual sectors, such as mining, finance or construction. Or the mix of industries in the economy can shift towards sectors that produce more or less output per hour.
Changes in national productivity growth essentially boil down to two factors: changes in productivity within sectors and a reallocation in hours worked between high and low productivity sectors. These effects can be disentangled through shift-share analysis.
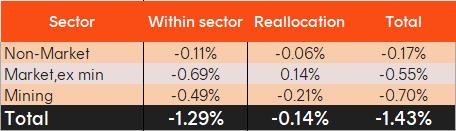
A shift-share analysis separates these two effects. It shows that changes within sectors accounted for 1.3 percentage points, or 90%, of the 1.4 percentage point slowdown in Australia’s productivity growth over the past decade. Changes in the allocation of hours worked between sectors had relatively little impact.
The non-market red herring
The market sector includes industries that produce goods and services sold in the economy, such as mining, manufacturing, finance and construction. The non-market sector includes services such as public administration, health and education, where measuring the value of output can be more difficult.
Let’s first dismiss a red herring. A lot of attention has been paid to the fact that the non-market sector has grown relative to the market sector in recent years and the lower level of productivity in the former (on average 20% lower than the national average) could be dragging down productivity growth estimates.
The evidence of this over the past decade is weak. As evident in the table above, the reallocation drag from the non-market sector was only 0.11pp in the past decade with slower productivity growth within these sectors taking another 0.06pp of national productivity growth – or a 12% contribution to the slowdown in productivity growth over the period.
How so? While it’s true that the non-market share of hours worked has increased in the past decade (from 23.7% to 27.7%), it increased by a similar amount in the previous decade (from 20.7% to 23.7%) – so the drag on national productivity levels from this shift has been broadly similar in both periods. As a result, the rise in non-market activity can’t account for the slowing in productivity growth in the latest decade – as it’s been a consistent ongoing drag for some time.
Mining, finance and the usual suspects
As seen in the table above, most of the slowdown in productivity growth has arisen from the market sector.
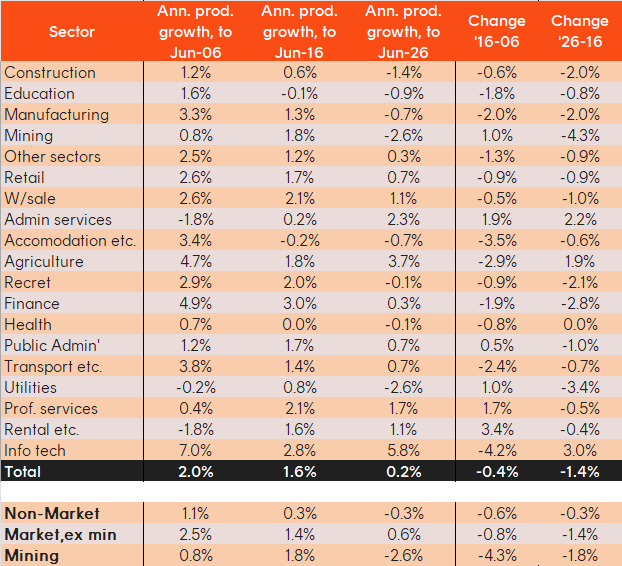
Indeed, as evident in the table below, a broad-based decline in productivity growth is evident across most sectors over the past decade. All but two sectors (information technology and agriculture) failed to lift annualised productivity in the decade to June 2026.
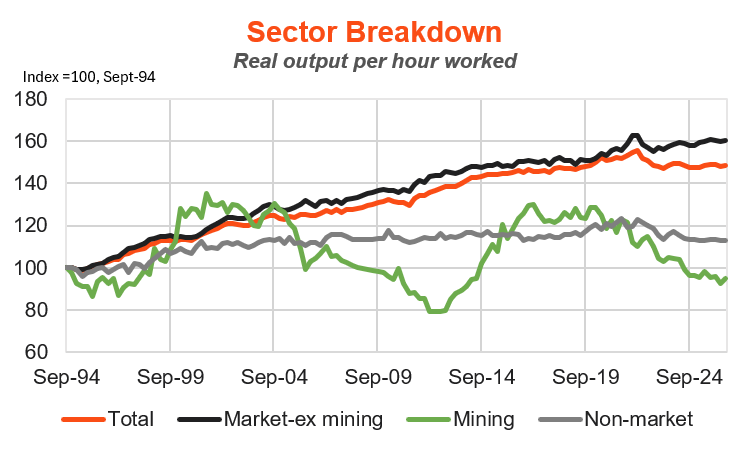
A sector creates a productivity drag when its productivity growth is lower than the national average, weighing on the overall result. Mining suffered the biggest decline, with annualised productivity growth declining from 1.8% to -2.6%, or 4.3 percentage points. That alone contributed 0.5pp, or around one third, of the national decline in productivity growth.
That said, as seen in the chart below, productivity in the mining sector often experiences wide swings over time – largely linked to the commodity price cycle. When commodity prices are high, mining companies have an incentive to develop harder-to-reach deposits. These projects require more labour and capital to produce the same amount of output, which can make measured productivity fall.
Source: Betashares, ABS
Less easy to dismiss is the slowdown in productivity growth across other “market, excluding mining” sectors, which contributed 0.7pp, or 50%, of the decline in national productivity. Among these sectors, the biggest drags came from finance, manufacturing, construction and utilities.
In the finance sector, some of the slowdown likely reflects a petering out of earlier strong productivity gains caused by strong credit growth post financial deregulation, along with new technologies like ATMs and growth in electronic payments. Increased regulation and new compliance requirements following the global financial crisis have likely contributed to the recent productivity slowdown. Finance enjoyed strong annualised productivity growth of 4.9% and 3.0% in the two earlier decades, though this slowed to only 0.3% in the latest 10-year period.
In manufacturing, a petering out of earlier strong gains from reduced trade protection and microeconomic reform is likely also at play. Annualised manufacturing productivity growth in the decade to June 2006 was a healthy 3.3%, though it slowed to 1.3% and -0.7% in the two following decades. Australian manufacturing also tends to suffer from lower scale economies than larger and/or more export-orientated manufacturing economies.
Construction sector productivity has also progressively slowed over recent decades, with a lack of scale (a bias toward smaller operators) and an increasingly complex approval process often cited as reasons.
In utilities, there’s been negative productivity growth of 2.6% in the past decade, with massive investments in clean-energy projects – to eventually replace ageing coal-fired electricity plants – a likely important reason. To the extent these investments are necessary to deal with climate change, and the investments will eventually bear fruit in terms of higher clean-energy in the future, the initial productivity slump is arguably more excusable, as in the case for mining.
Another source of poor productivity in the utilities sector has been so-called “gold plating” whereby energy distributors were incentivised to invest heavily in poles and wires as they could then charge higher prices. Even here, however, some might argue these investments improved supply reliability – an effective quality improvement not captured in the productivity estimates.
A general loss of dynamism
Economic dynamism refers to how actively businesses are created, expanded, challenged and replaced.
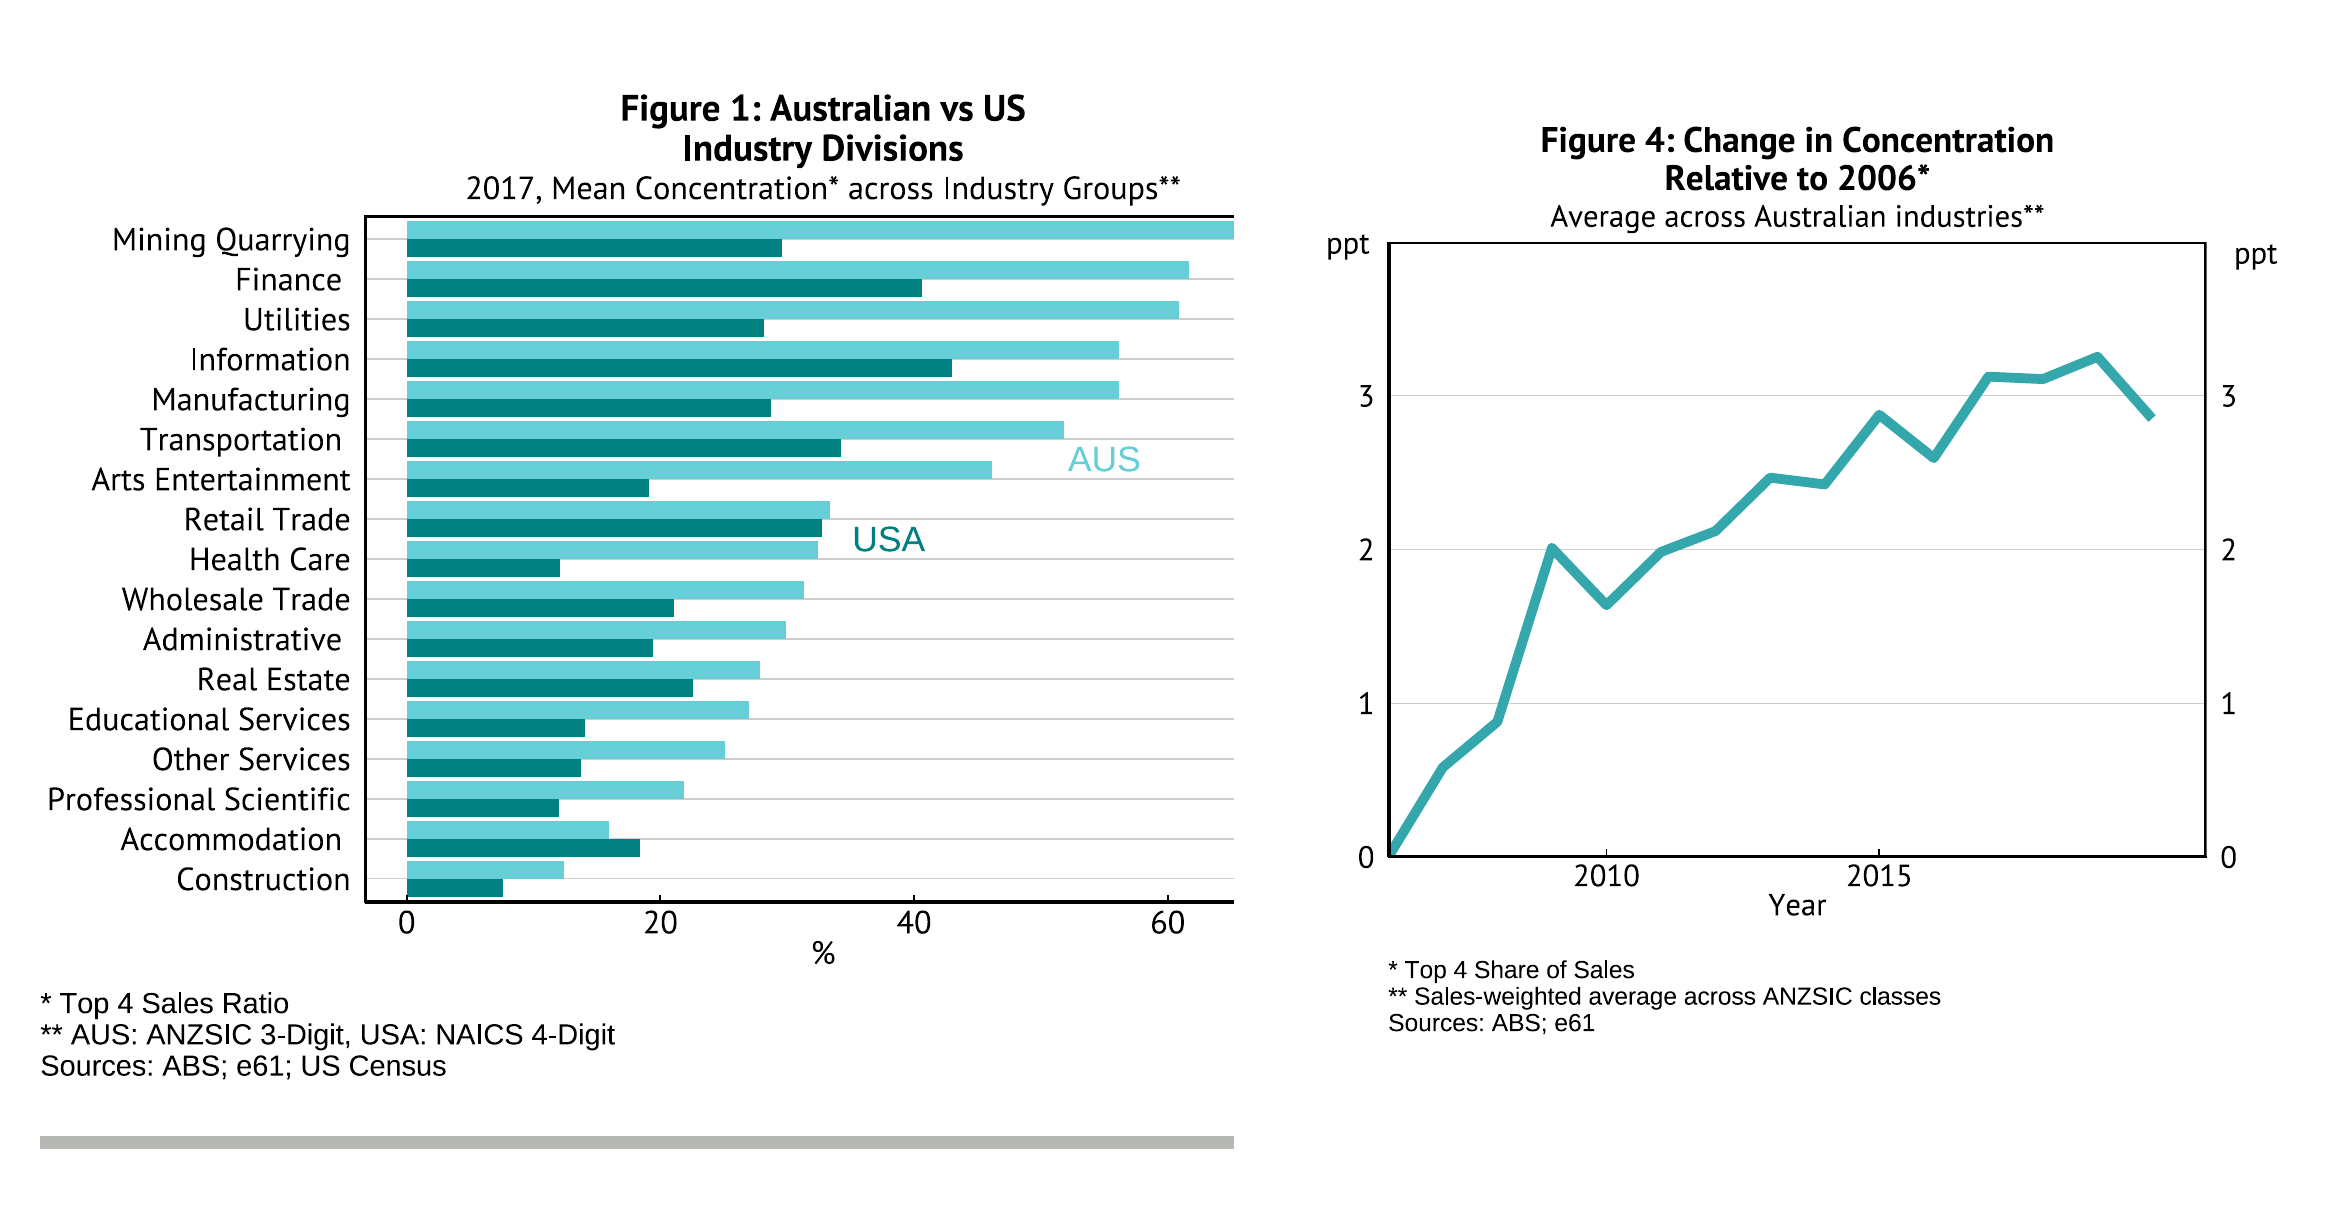
Many official reports on Australia’s productivity slowdown have noted a general loss of “economic dynamism1”. By way of example, the rate of entry and exit of firms has slowed over recent decades, as has job turnover (workers are less inclined to switch jobs).
According to e61 research, industry concentration also tends to be higher in Australia than the United States and has increased in recent years – especially in areas like retail and transportation.2
Conclusion: beware a loss of entrepreneurialism
In short, Australia’s productivity slowdown over the past decade reflects several factors – some more excusable than others. A good chunk reflects an understandable slump in mining sector productivity due to high commodity prices.
Other arguably excusable elements are the costs of transitioning to cleaner and more reliable energy and more regulatory compliance in the finance sector. The rise in non-market services appears to be a red herring, as its drag on national productivity growth has been around for more than a decade.
Less excusable is a broad-based decline in productivity growth across a range of market sectors. Part of this reflects a slowing in productivity after earlier reforms led to a one-off productivity boost in some areas like finance and manufacturing – the shame is that productivity-enhancing reforms in these areas have not persisted.
The greater underlying concern, however, is the apparent loss of economic dynamism – with markets becoming more concentrated and less subject to competition by new entrants. It’s against this background that the Federal Government’s recent increase in the complexity and level of capital gains tax payable on new business start-ups threatens to make matters worse, rather than better.
