

Key global developments in October
- A correction in technology stocks was a major feature of the month, which helped drag down global equities, some commodity prices and bond yields, notwithstanding even higher energy prices. The $US firmed which, as with bonds, likely reflects safe-haven flows.
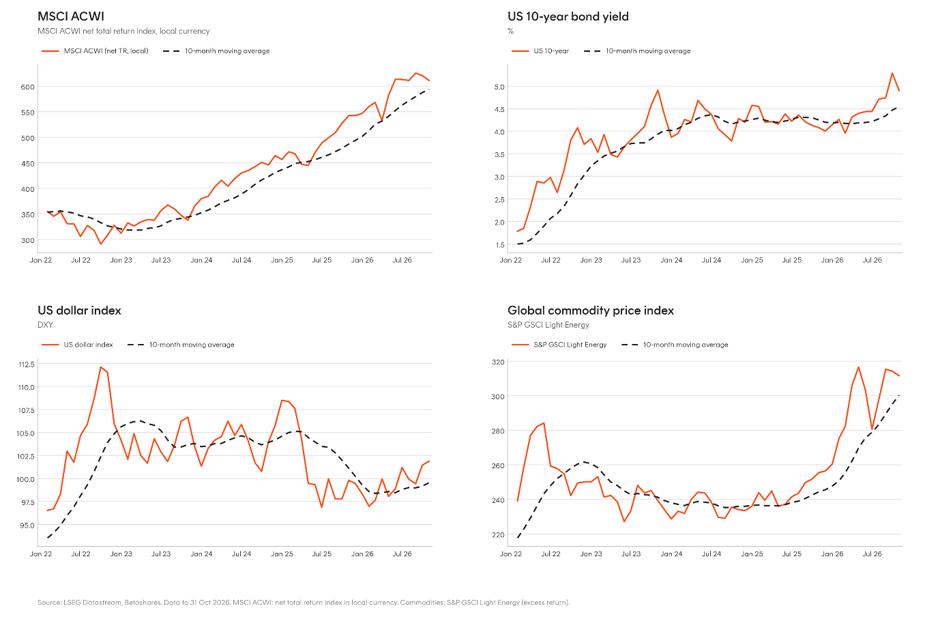
- Military conflict in the Middle East escalated further in October, with Iran stepping up attacks on shipping and Houthi strikes on Saudi Arabia’s oil facilities continuing, while an “energy ceasefire” between Russia and Ukraine failed. Brent crude rose a further 14% to end the month at $US118/barrel.
- AI-related stocks came under renewed selling pressure. Strong earnings results were overshadowed by concerns over soaring AI capital spending and how it will be financed, with both Alphabet and Meta reporting negative free cash flow. The Nasdaq-100 fell 6.7%.
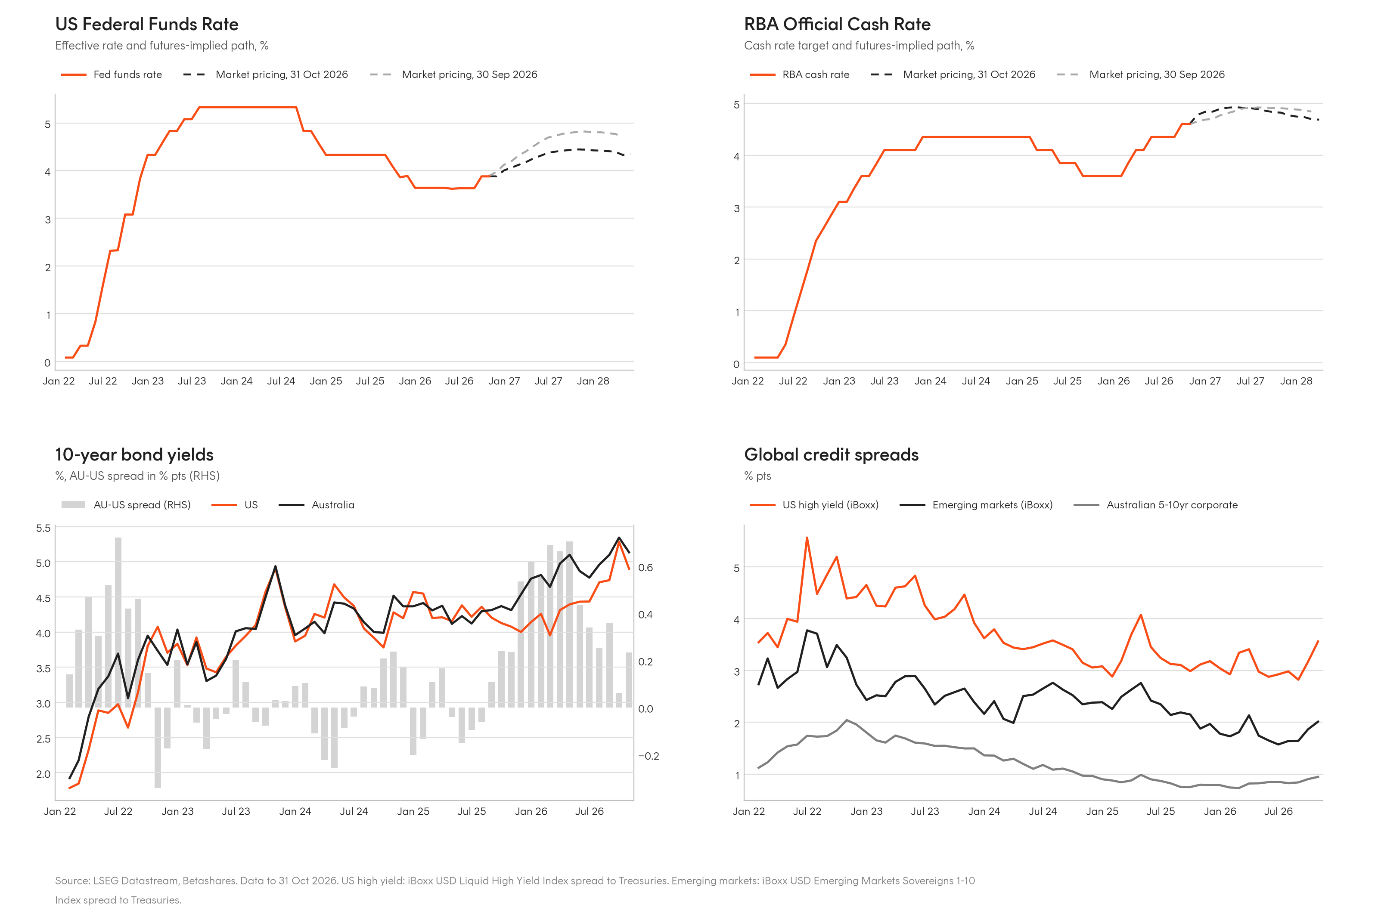
- Global central banks largely paused after September’s wave of tightening, though most kept the door open to further hikes. The US Federal Reserve delivered a “hawkish hold”, leaving rates at 3.75-4.00%, with two members dissenting in favour of a 0.25% hike. The European Central Bank held rates at 2.5% but pointed to a December hike, while the Bank of Japan held at 1.25%.
- US economic data remained firm, with a 0.3% rise in the September core CPI, 3.4% annualised growth in Q3 GDP and jobless claims near a 57-year low, though payrolls rose by a weak 29k in September. Bond yields nonetheless eased back from their late-September highs as investors sought safety amid weakness in technology stocks, with US 10-year yields falling back below 5%.
- In Australia, inflation pressures intensified. The Q3 trimmed mean CPI rose 1.0%, above the RBA’s 0.8% forecast, while annual headline inflation rose to 4.3%. The RBA raised the cash rate a further 0.25% to 4.85% at its early November meeting, following its last hike in September. The economy remained soft, however. Employment fell 39k in September and the unemployment rate rose to 4.7%, a post-COVID high. House prices kept falling, and both business and consumer confidence weakened further.
Interest rates
- US rate hike expectations eased back over the past month after the Fed held rates steady. Markets now expect the Fed funds rate to reach around 4.4% in 12 months, down 0.34% from a month earlier – still implying two further rate hikes. US 10-year bond yields fell 0.38% to 4.90%. Markets attach a 73% chance of a rate hike at the next Fed meeting in December.
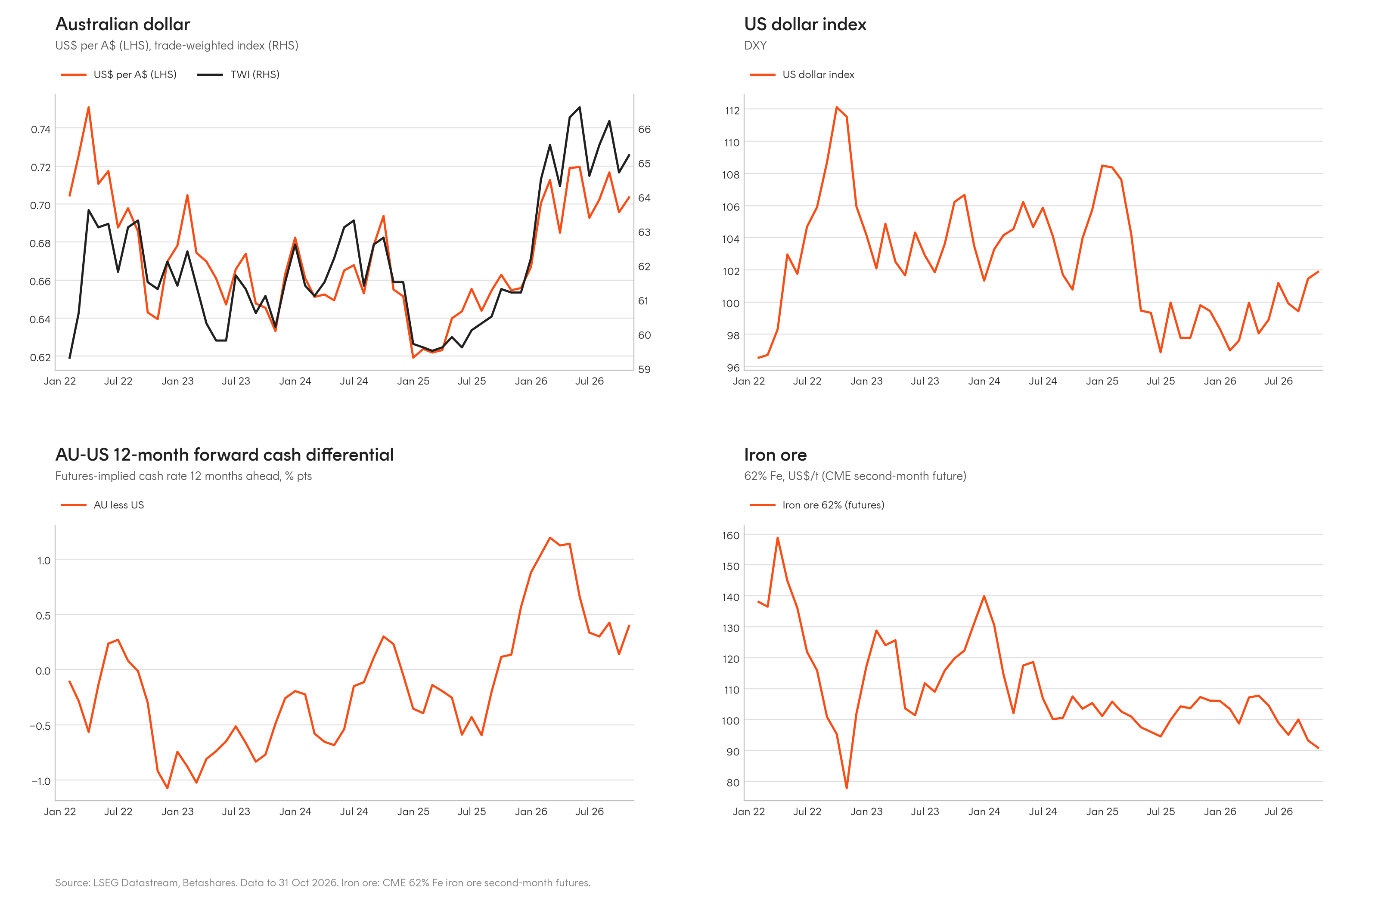
- In Australia, the market’s one-year ahead cash rate expectations eased 0.09% to 4.8%, still implying one further rate hike. After the firmer Q3 CPI, the RBA duly raised rates at its Melbourne Cup Day meeting, though three of the nine Board members voted to hold. Local 10-year bond yields fell 0.21% to 5.14%, with the spread over US 10-year rates widening to 0.23%.
- US high yield and emerging market spreads widened further in the month amid concerns over AI-related debt, though local credit spreads remained contained.
Exchange rates
- The $A rose 1.1% against the $US in October to US70.4c, and by 0.8% in trade-weighted terms. This was despite a slightly firmer $US (+0.4%), as the firmer Q3 CPI lifted expectations of a further RBA rate hike while US rate expectations eased. The gap between expected Australian and US interest rates in 12 months’ time widened to 0.4% from 0.1% a month earlier.
Commodity prices
- The benchmark index of global commodity prices* eased 0.8% in October after being broadly flat in September, as a further rise in oil and gas prices were more than offset by weakness elsewhere.
- Gold prices fell a further 6.4%, as expectations of further Fed tightening and a firmer $US continued to weigh on the non-yielding metal. Oil was again the standout, rising 14% to $US 118/barrel as attacks on Middle East shipping and oil facilities intensified.
- Iron ore fell 2.3% and agricultural prices fell 7.2%. Industrial metals eased 1.8%, even though AI, defence and clean energy investment continue to support demand. These positives were offset by concerns around the tech pull back in October.
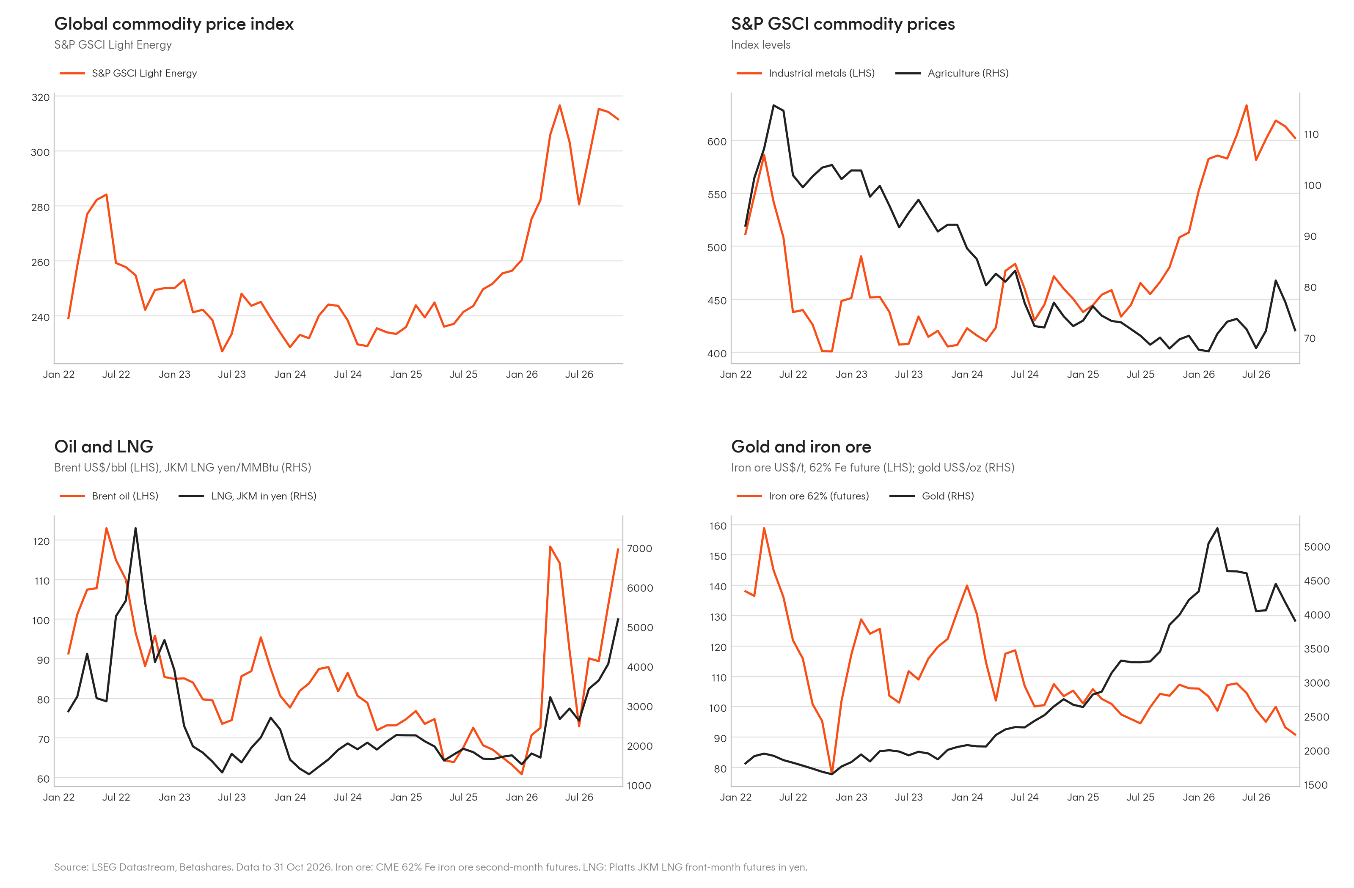
*Represented by the S&P GSCI Light Energy Index, which includes a range of prices covering energy, metals, agriculture and livestock.
Global equities
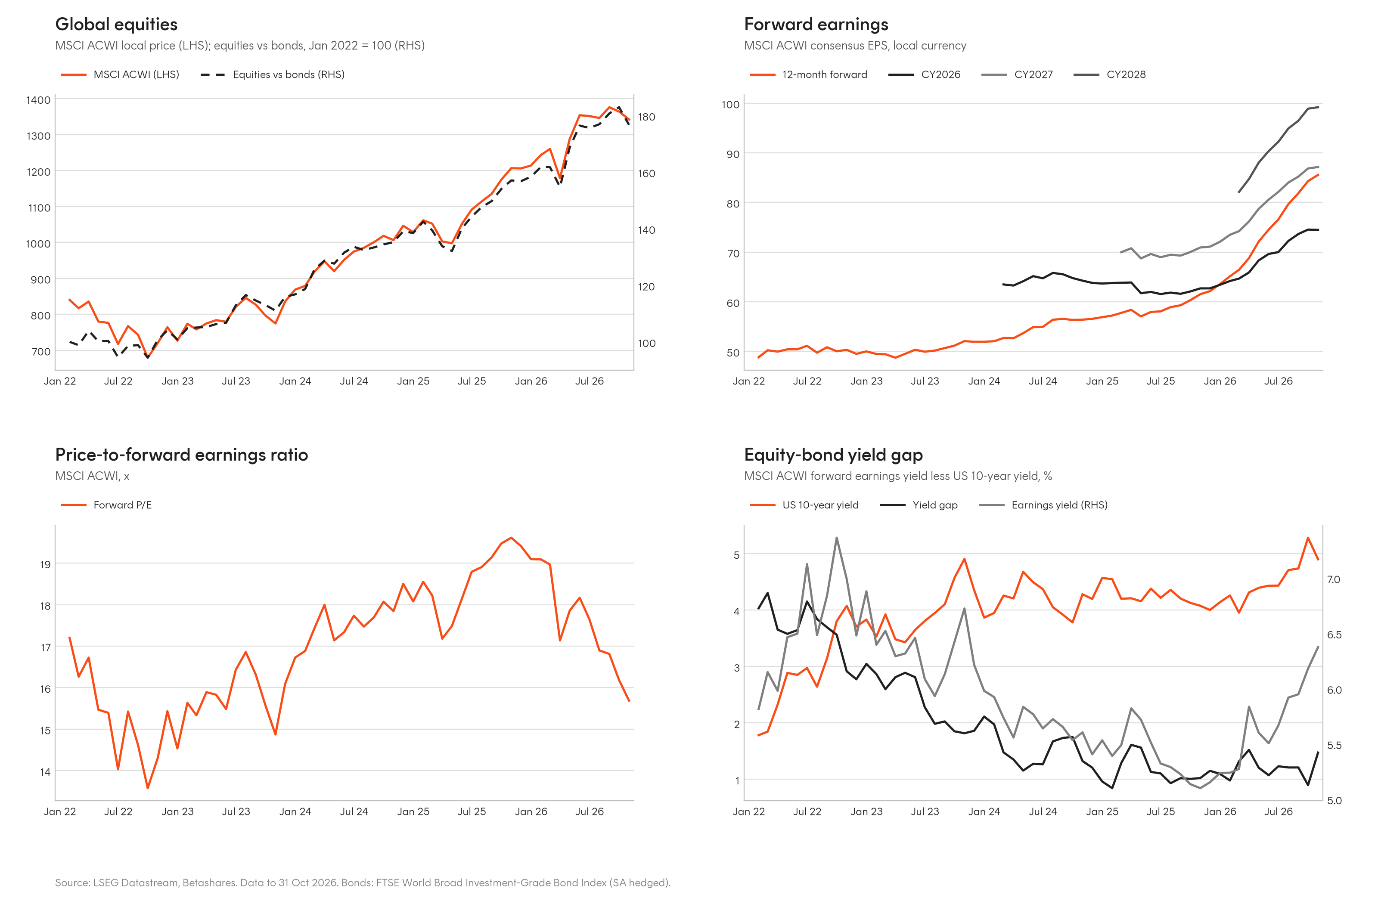
- Global equities returned -1.6% in local currency terms and -2.7% in unhedged $A terms, due to the firmer $A.
- The decline reflected a further 3% fall in the forward PE ratio to 15.7 as AI-related technology stocks sold off. This more than offset a 1.5% gain in forward earnings. With bond yields also easing, the global equity risk premium widened to around 1.5% – though this is still at the low end of its range in recent years.
- All of the major markets fell in the month. The S&P 500 (-0.9%) held up best, as gains broadened beyond big tech, with the equal-weighted index outperforming its market-cap weighted counterpart by 3.3%. Eurozone equities (-1.7%) also fell modestly, while Japan (-5.2%) and emerging markets (-8.0%) fared worst, reflecting their now heavy exposure to AI-related technology.
- Global earnings expectations remain upbeat, with 16% expected further growth in forward earnings by end-2027. PE valuations are at their lowest level since late 2023, though further AI-related volatility and a renewed rise in bond yields remain the key threats to the outlook.
Australian equities
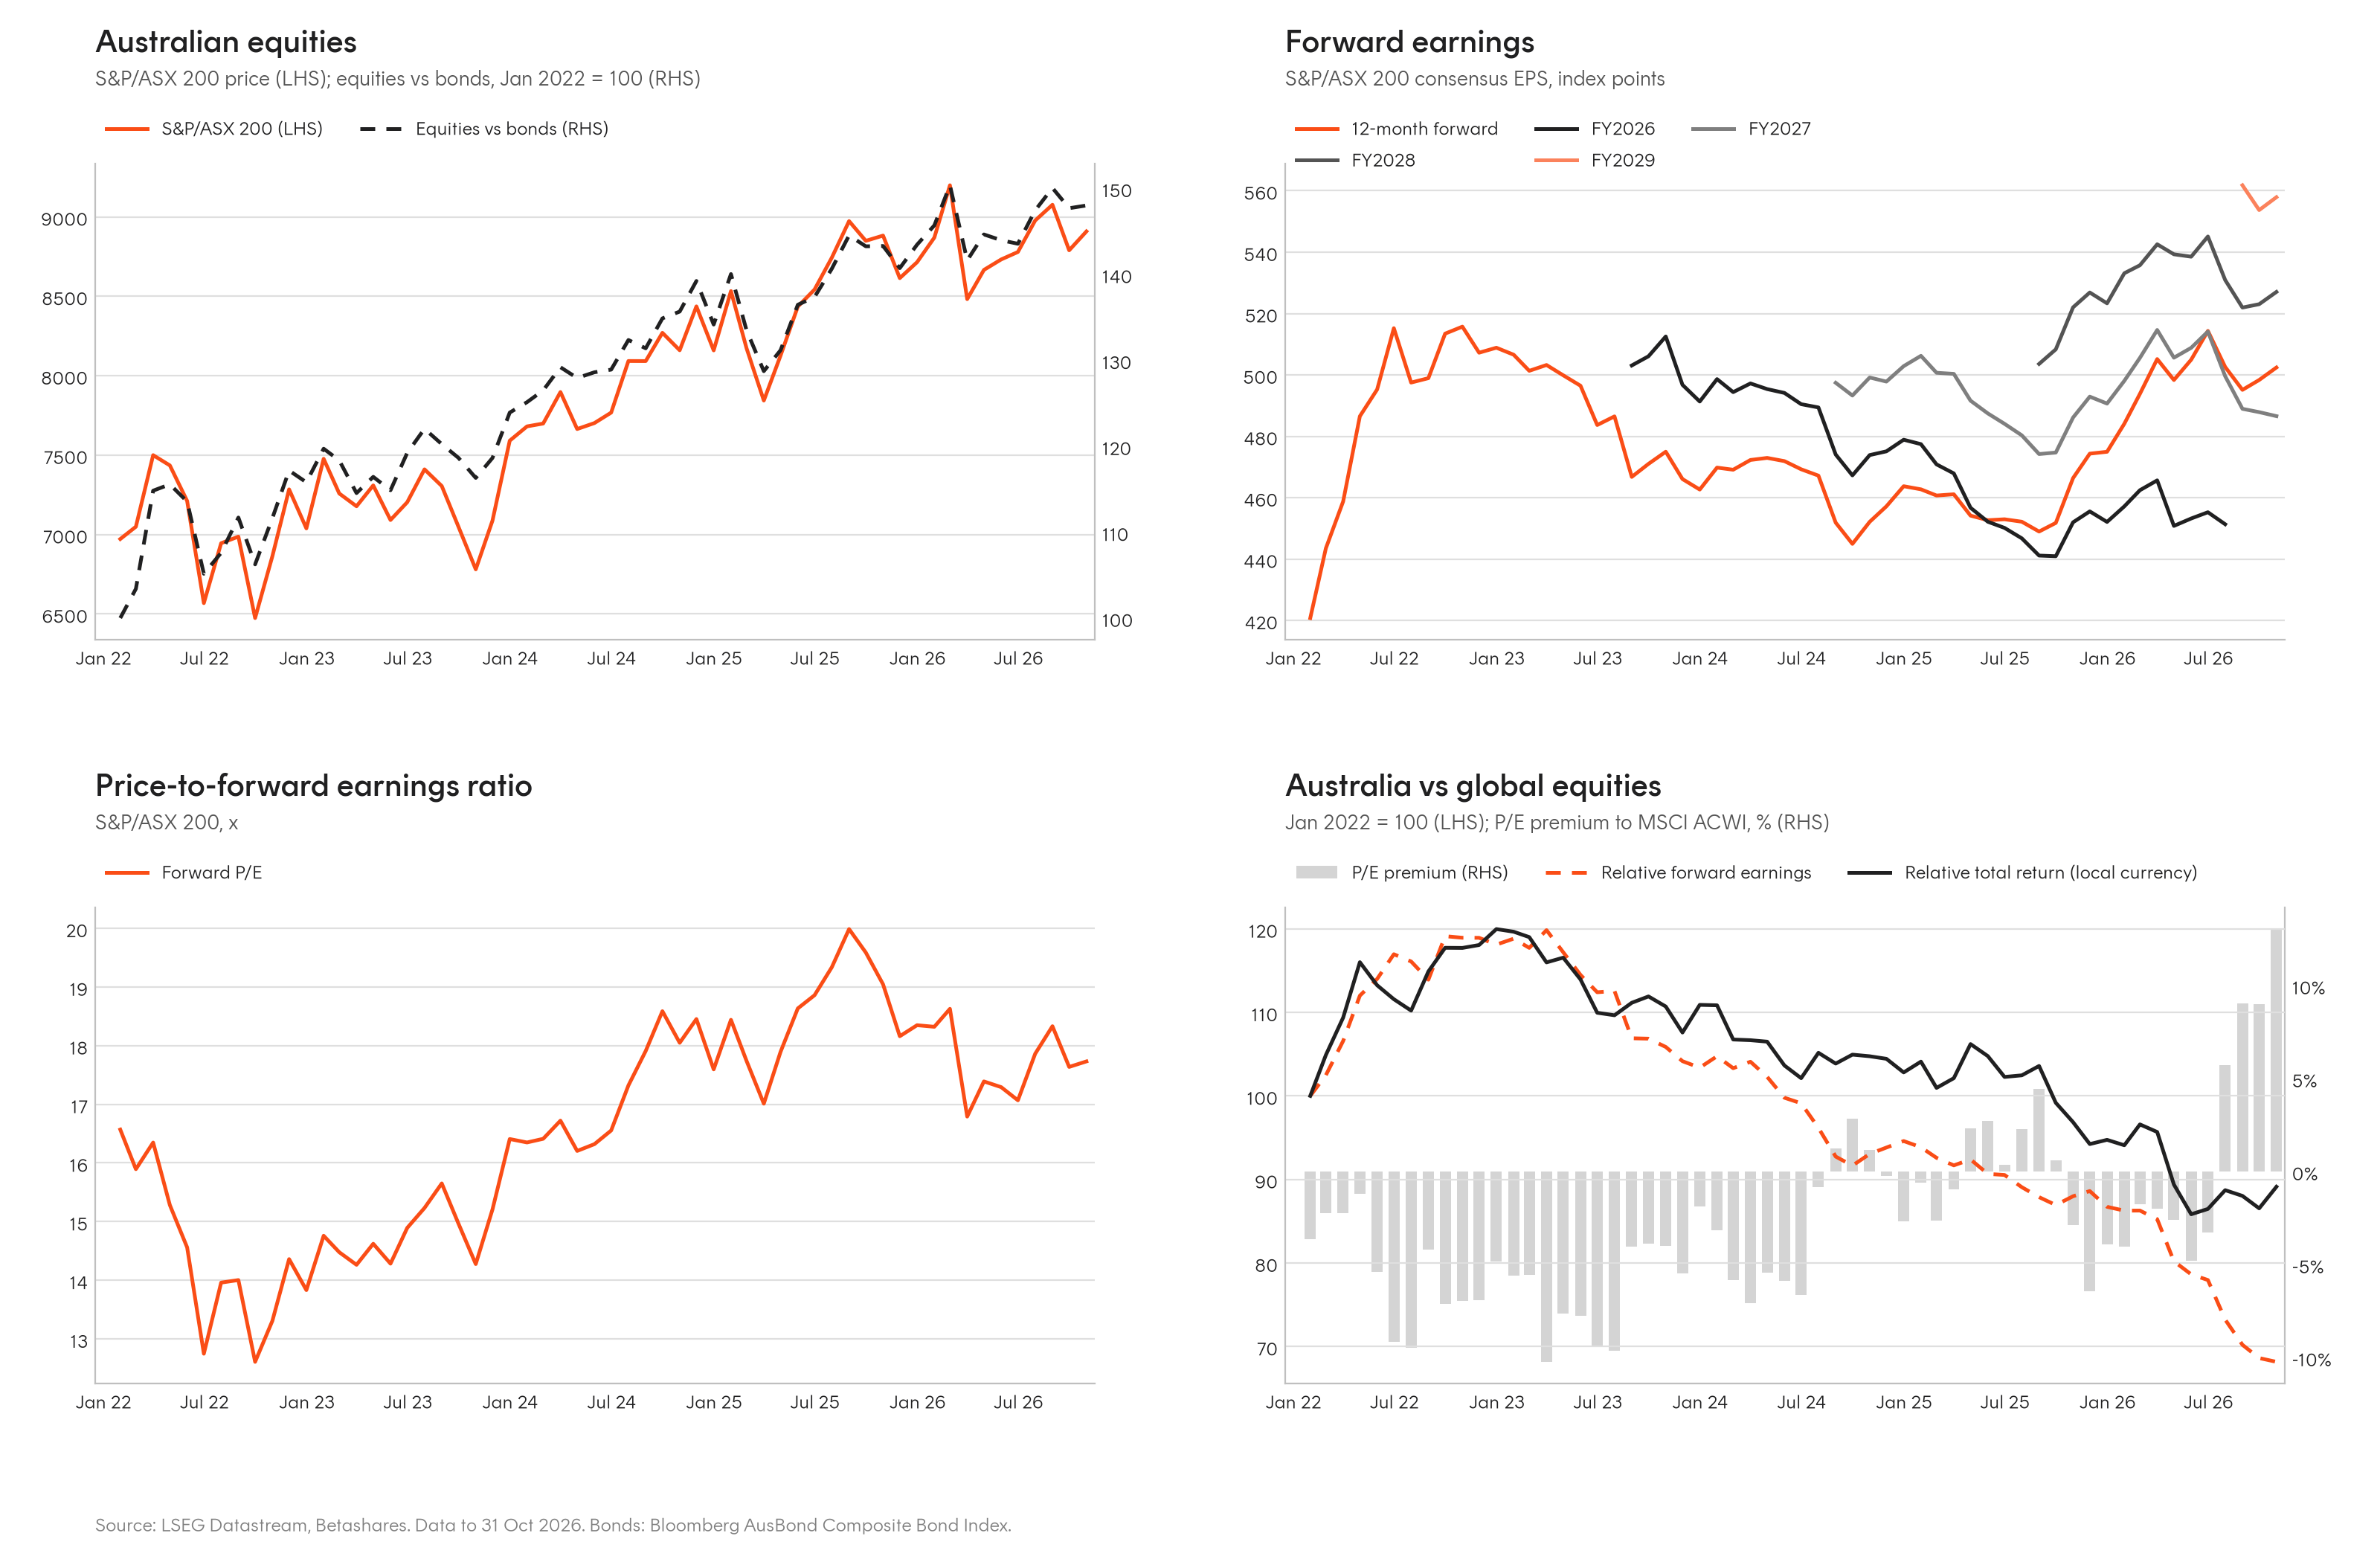
- Australian equities returned 1.4% in October, as the forward PE ratio edged up 0.5% to 17.7 and forward earnings rose 0.8%.
- Current earnings expectations are consistent with 8% growth in forward earnings by end-2027. That’s still half that’s expected for global markets – and more vulnerable to downgrades given the soft local economy and rising interest rates.
- At 17.7, the forward PE ratio ended October at a 13% premium to global markets – its widest in at least three years. The local market’s low exposure to AI-related technology allowed it to do a “Steve Bradbury” in October, though its weaker earnings outlook and relatively expensive valuations still point to underperformance versus global peers over the coming year.
Equity themes/trends
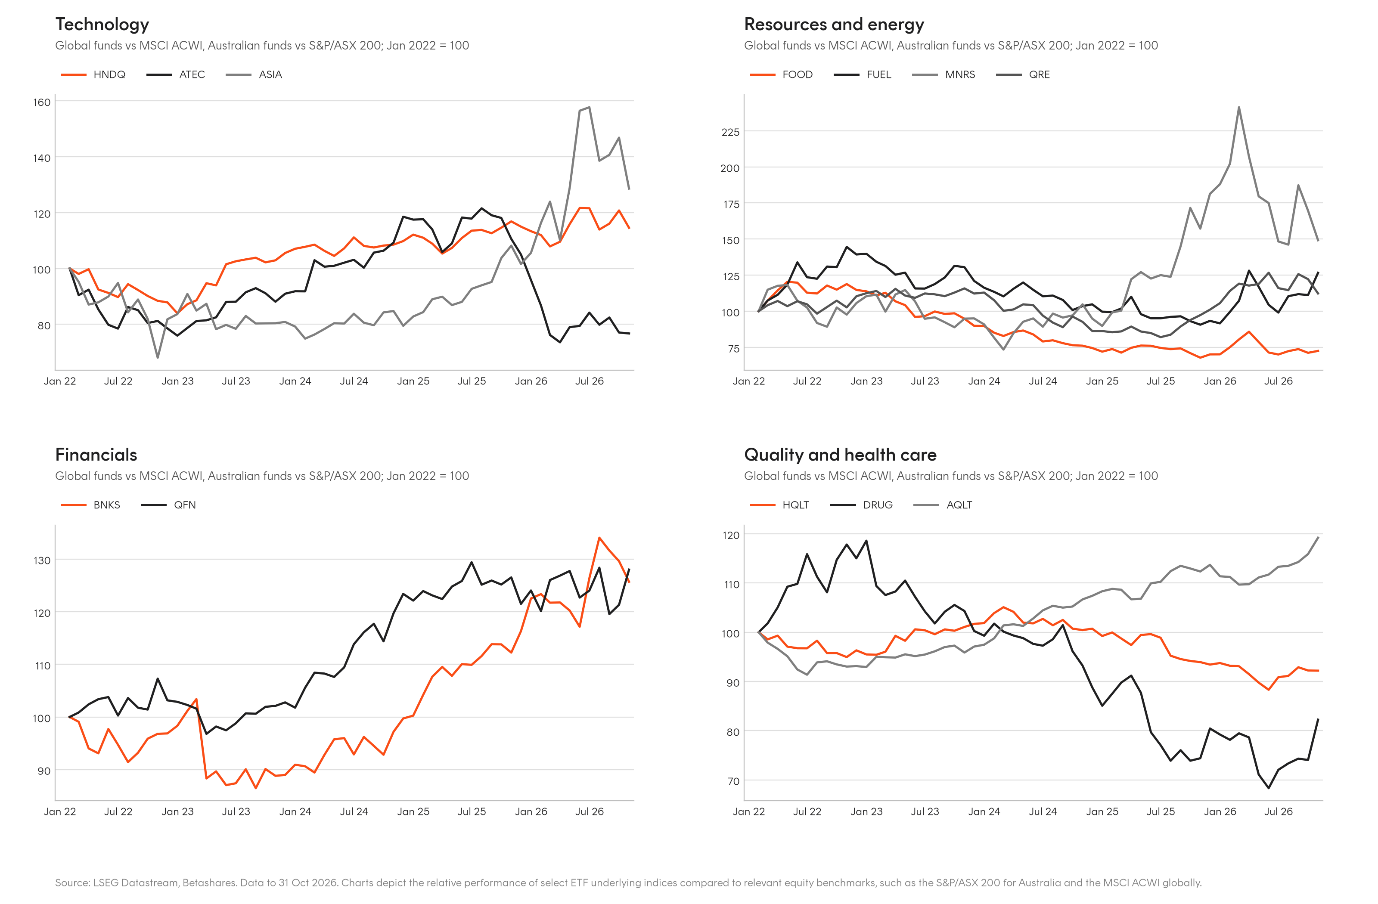
- Technology gave back some of its recent outperformance in the month, with the hedged Nasdaq-100 (HNDQ Nasdaq 100 Currency Hedged ETF) down 6.5%. Unhedged Asian technology (ASIA Asia Technology Tigers ETF) declined 14.8%. Cybersecurity (HACK Global Cybersecurity ETF, -3.0%) held up relatively better, while local technology stocks (ATEC S&P/ASX Australian Technology ETF, +0.9%) edged higher.
- The commodity area was mixed, with FUEL Global Energy Companies Currency Hedged ETF up 12.0% on higher oil prices, while MNRS Global Gold Miners Currency Hedged ETF and QRE Australian Resources Sector ETF fell a further 13.4% and 6.8% respectively.
- Local financials (QFN Australian Financials Sector ETF, +7.0%) became something of a safe haven in the month, while global banks (BNKS Global Banks Currency Hedged ETF, -4.5%) underperformed.
- Global health care (DRUG Global Healthcare Currency Hedged ETF, +9.3%) rebounded strongly in the month. Local quality (AQLT Australian Quality ETF, +4.3%) also outperformed, while global quality (HQLT Global Quality Leaders Currency Hedged ETF, -1.6%) performed in line with the global market.
Past performance is not indicative of future performance of any index or ETF.