


Precis: Australian equities have become the most challenging part of a lot of investors portfolios. We unpack why along with a practical investment approach.
Australian equities have materially lagged global peers, both year to date and over longer-term horizons, returning 4.4% over the past twelve months against 20.4% for global shares1.
Australia’s lack of direct AI beneficiaries, partly offset by the related resource rally, has left most of our domestic market looking limp in the face of supercharged earnings and returns overseas.
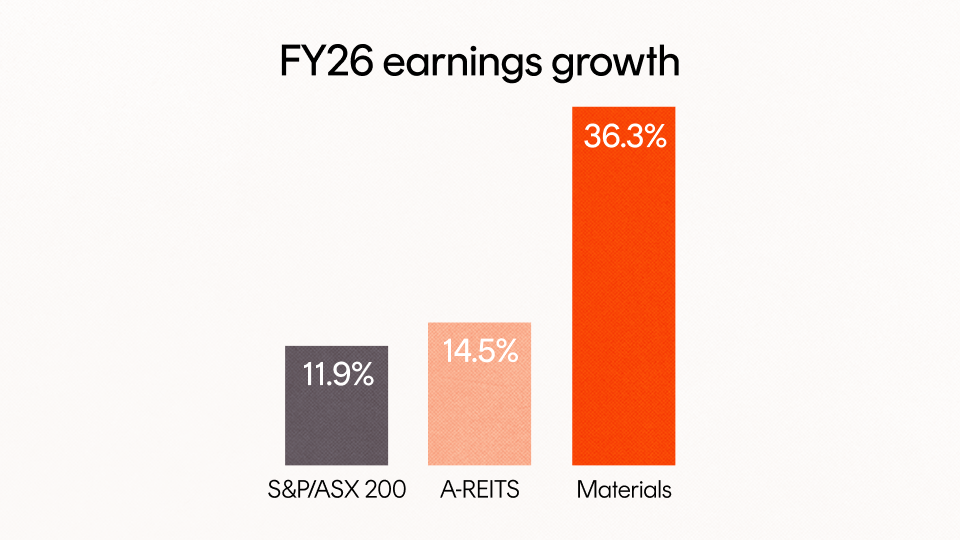
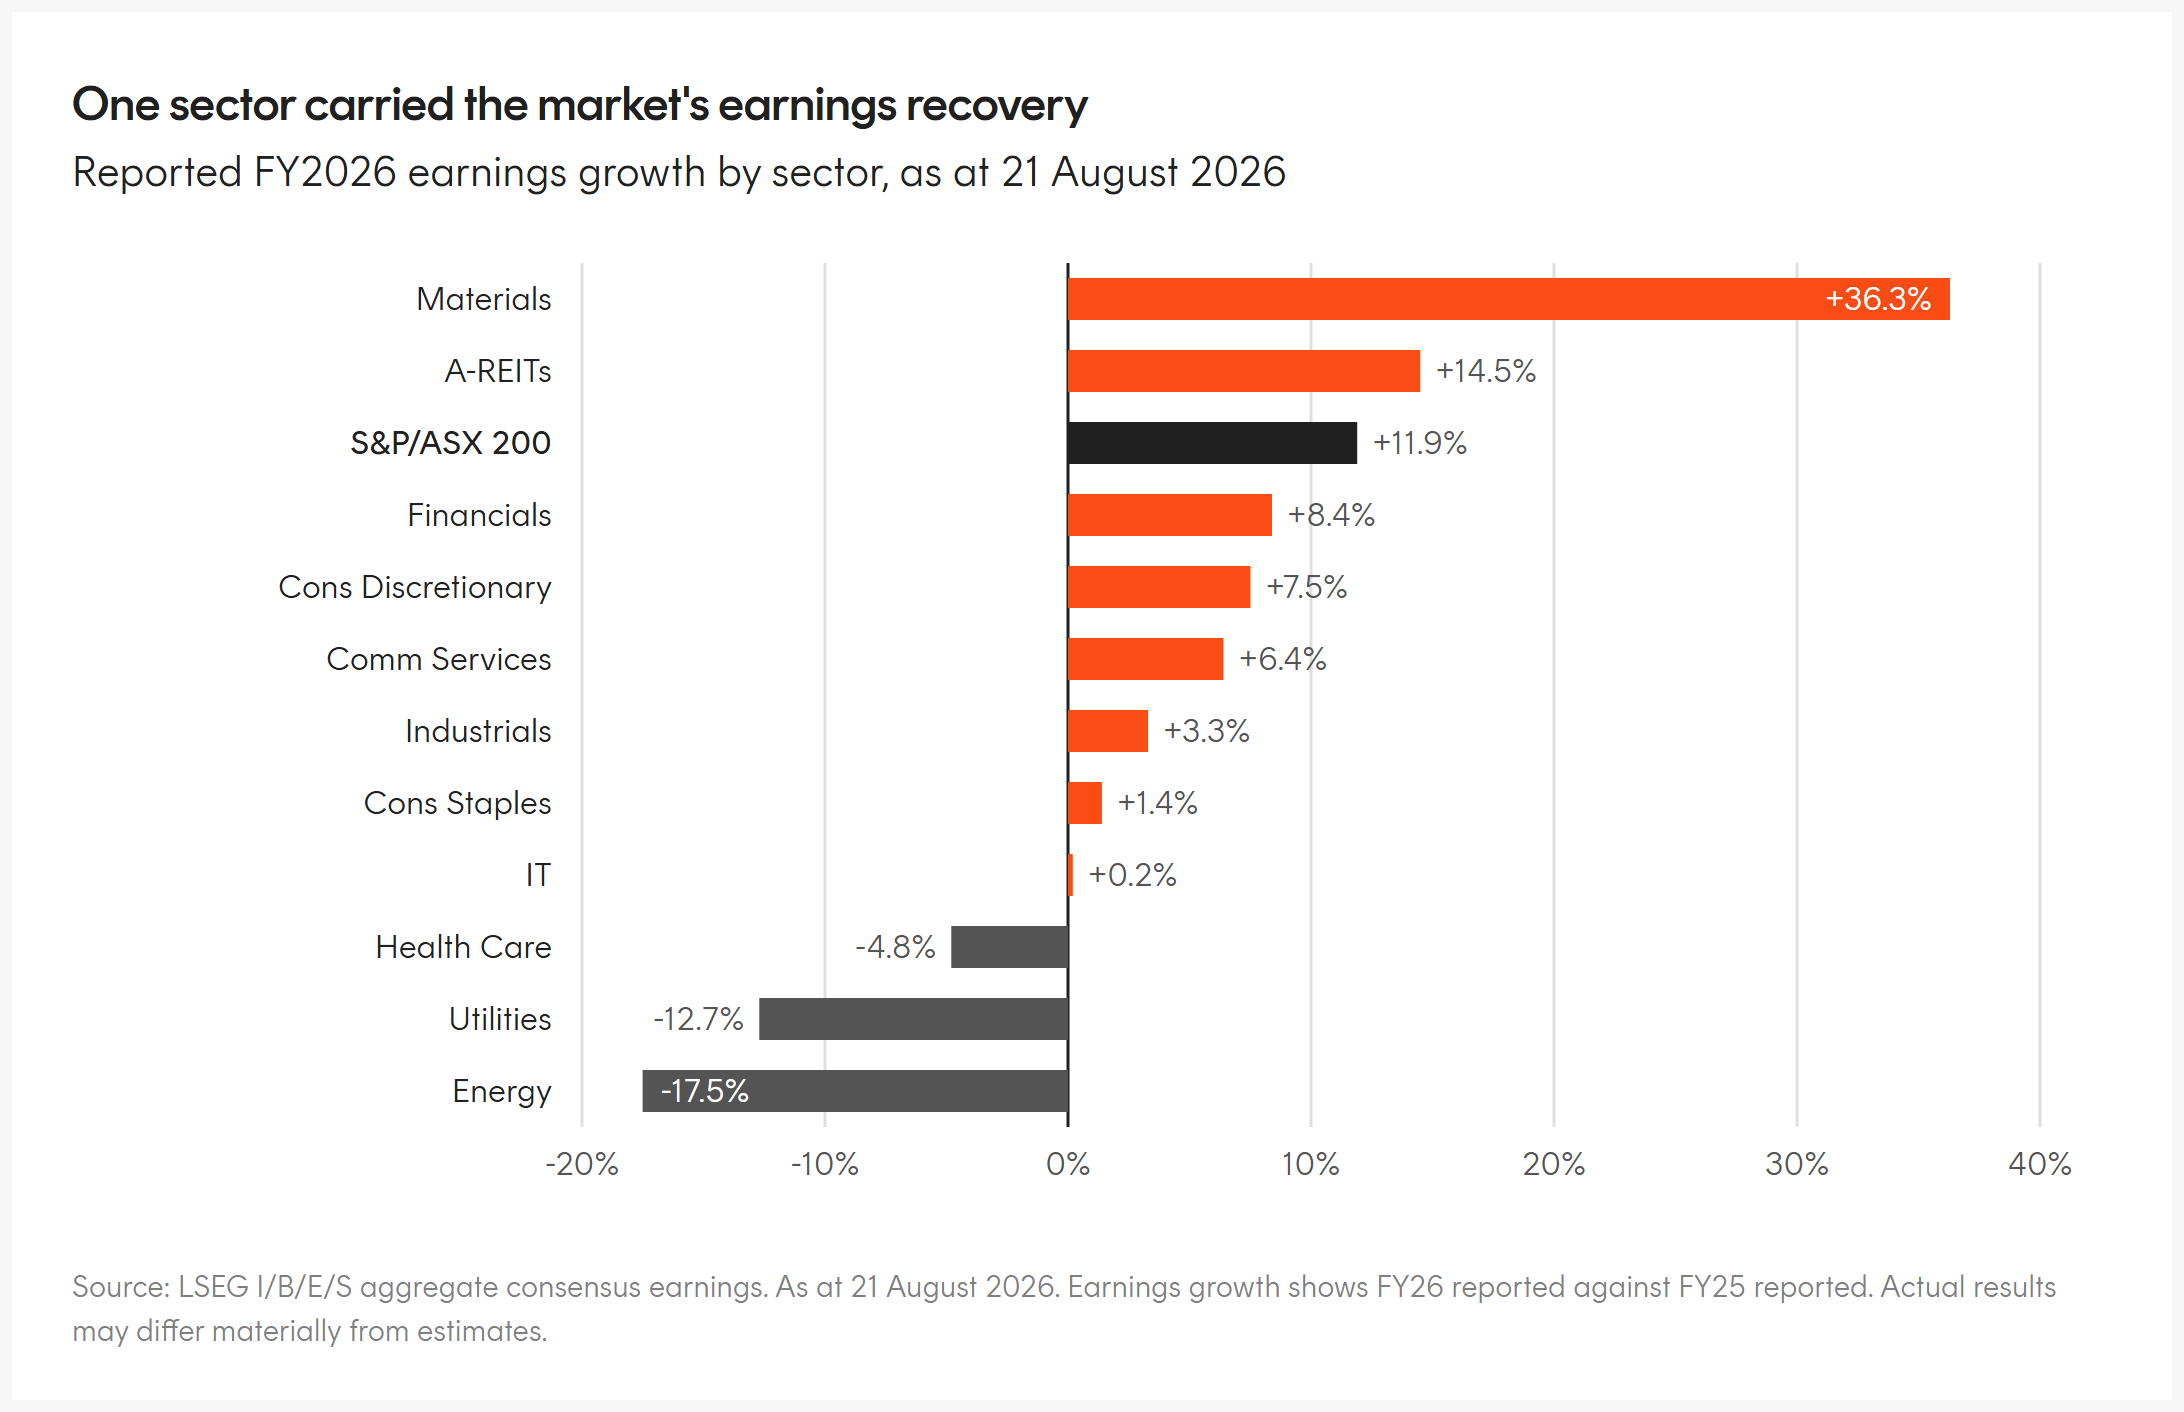
The Australian market entered 2026 on the back of three consecutive financial years of negative earnings growth. So, a reported 11.9% growth rate for FY26 is something to rejoice in2. Materials are by far the biggest contributor to this turnaround, exclude the sector and the market would have grown just 3.4%3.
Dr Copper replaces Chinese medicine for Australia’s resources sector
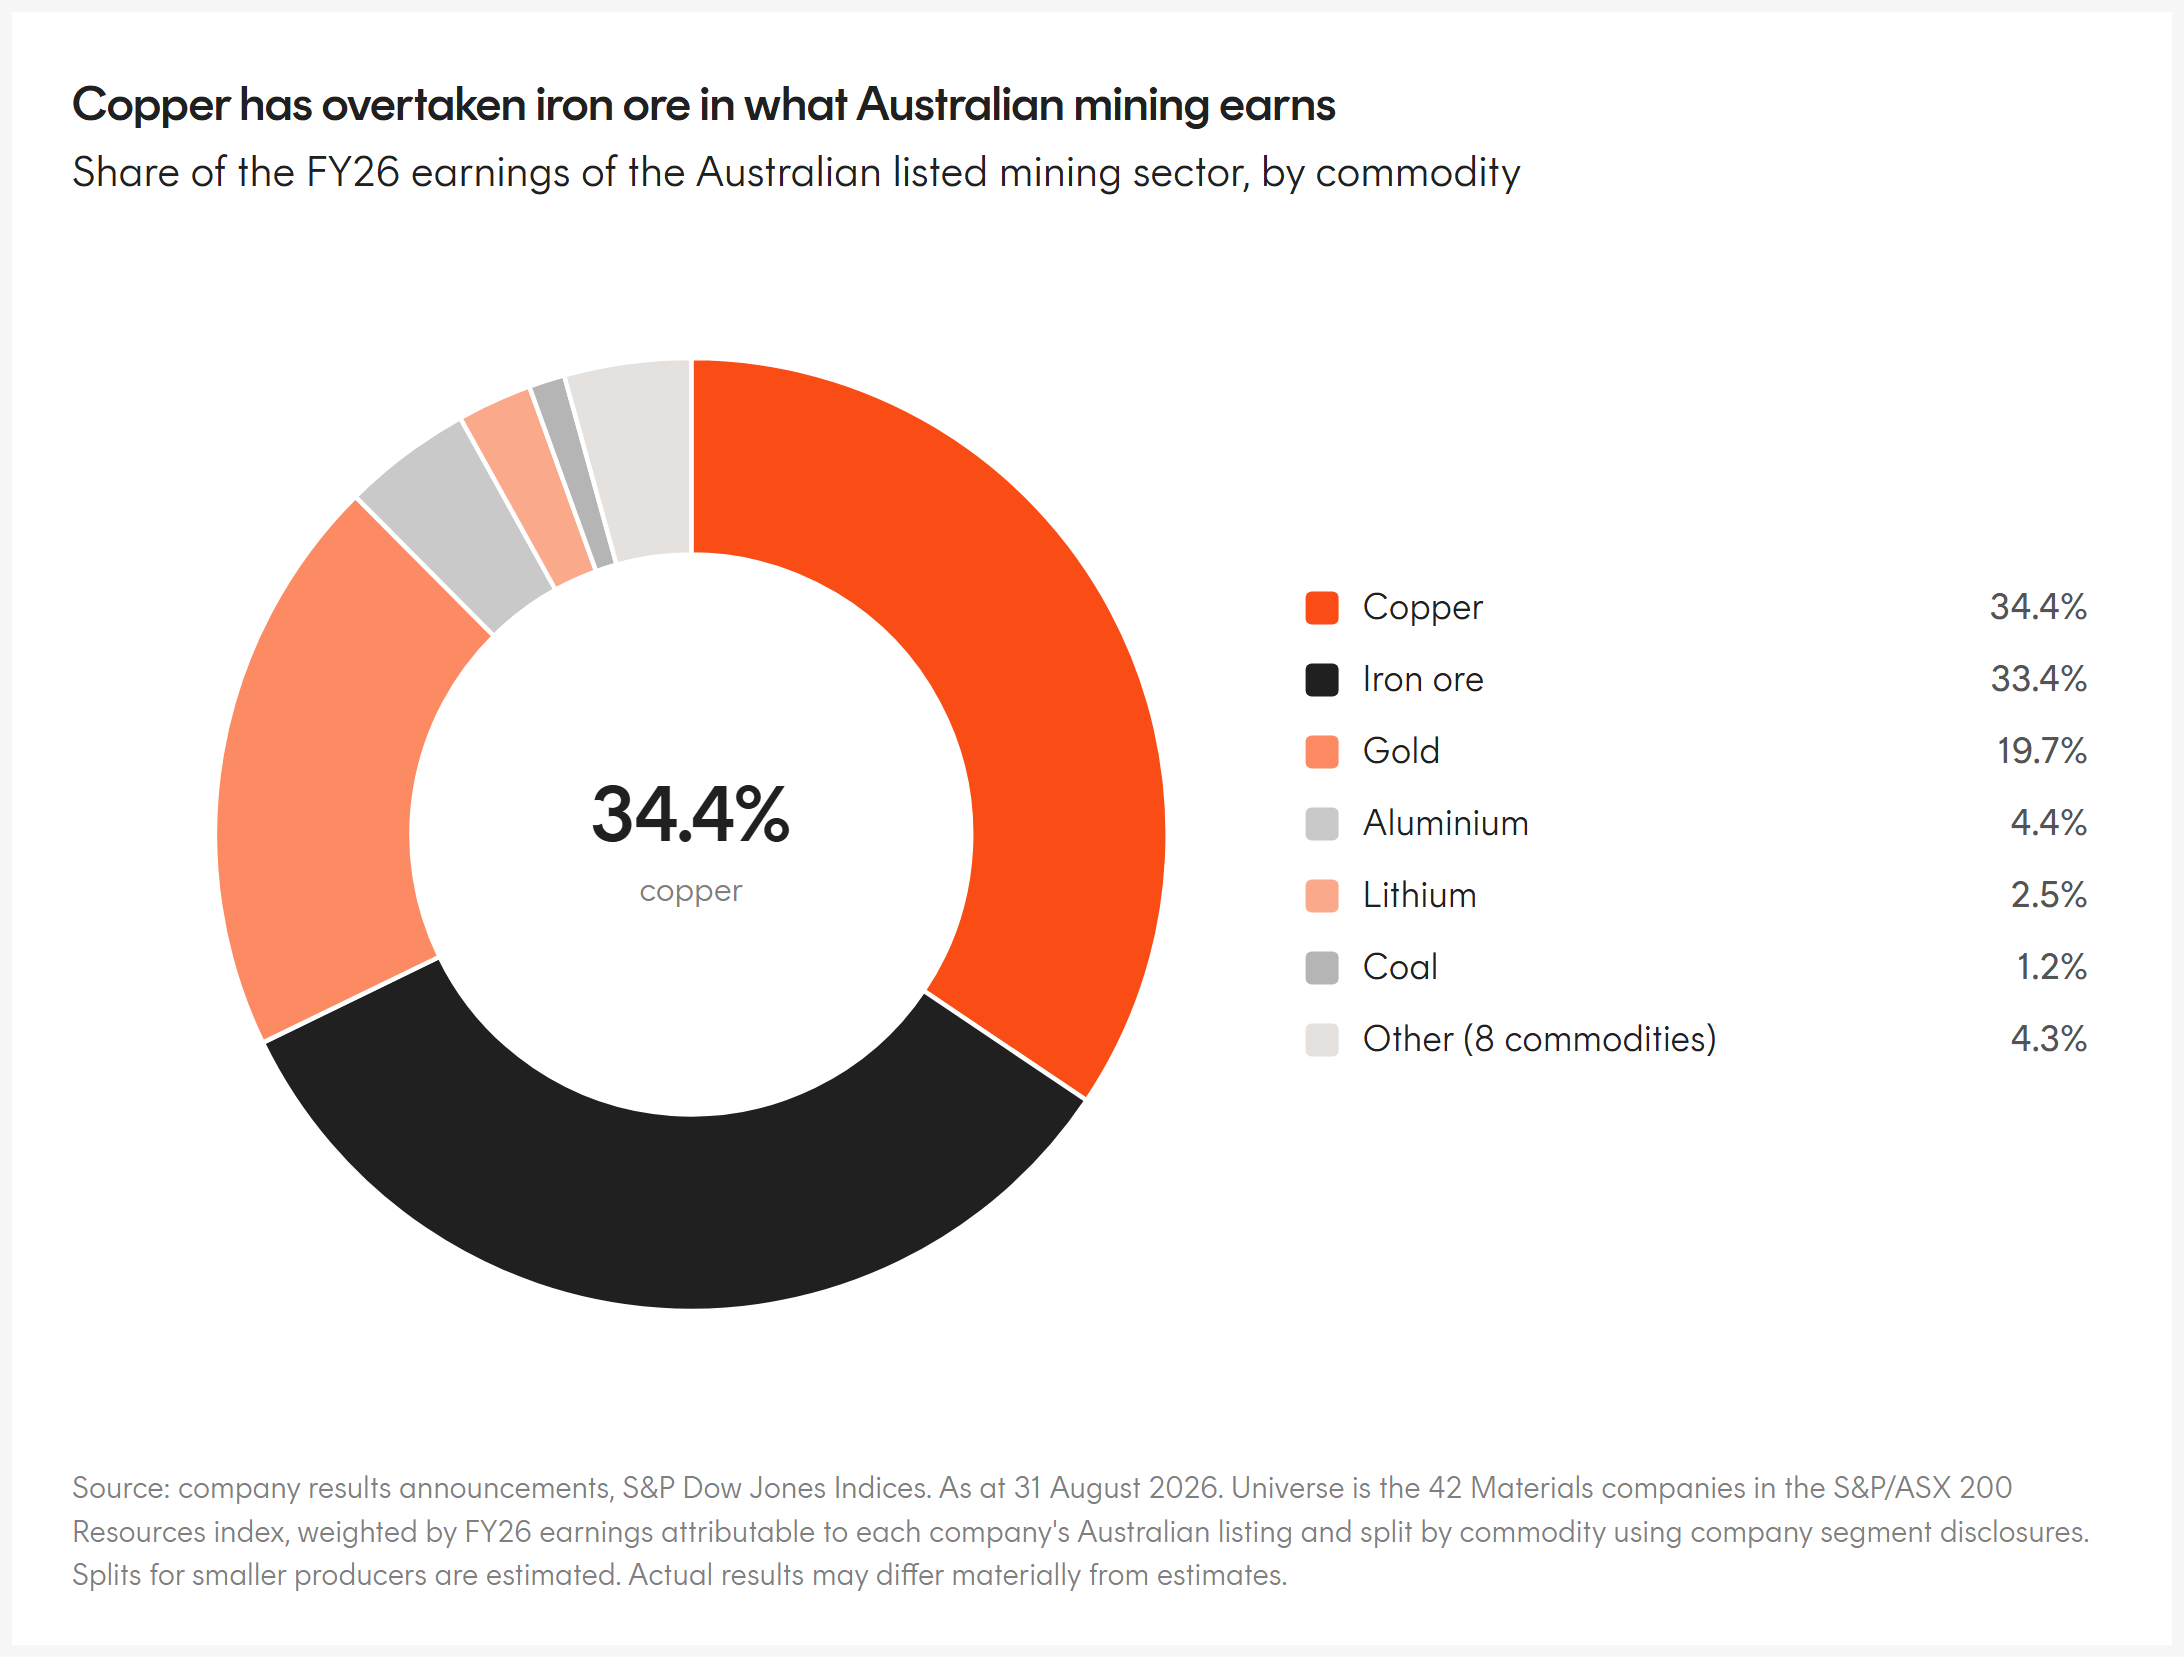
Led by BHP and Rio’s strategic pivots Australia’s materials sector is much less reliant on iron ore than it once was. BHP’s FY26 result in August confirmed copper at 54.2% of segment earnings against iron ore’s 43.3%4, the first full year copper has been the majority, while Rio reported in late July revealing their copper earnings were up 84% year on year and now just behind iron ore earnings5.
The surging copper price, related to the green energy transition and AI buildouts, has therefore been a significant positive contributor to the sector’s performance, alongside a higher gold price than in recent years.
Budget woes for the Big 4 mortgage hose
Australia’s other majors, the big banks, are not faring as well.
Since the GFC international banks have diversified into higher-growth businesses including payments, capital markets and wealth management. These global peers are seeing historic growth and profits.
Australia’s Big Four took a different path. They simplified, exited adjacent businesses and doubled down on home lending, a mature market now facing fresh headwinds following the Federal Budget’s tax changes.
Australian financials sit at expensive price to earnings levels, led by CBA, complicating the challenged earnings outlook for investors.
Turning to the remainder of the market, the outlook has deteriorated since the Federal Budget.
As an example JB Hi-Fi reported record sales and a higher full-year profit, but sold off on its reporting day as management flagged a challenged path ahead.This was a common story across consumer facing companies where fears of weak consumer confidence and margin pressures, due to higher input costs, hurt share prices even if their sales results were ok.
Investment implications: How to navigate the challenged Australian equity market
Australian equities have become a challenging part of investor portfolio. Whipsawing performance between the two major sectors, materials and financials, and weaker returns compared to overseas markets has a lot of investors wondering if they should allocate less domestically.
We believe there is another option: taking a more targeted approach to investing in Australian equities.
Rather than relying on the broader index alone, investors can choose to invest through the growing range of passive factor ETFs available in the Australian market.
For example, the AQLT Australian Quality ETF focuses on quality. Rather than simply holding the biggest names on the ASX, it screens the market for companies with consistently high returns on equity, stable earnings and relatively low debt. The sorts of businesses that tend to be better placed to keep growing profits when conditions get tougher. In a market where earnings expectations are being cut, owning companies with more reliable earnings can help.
The QOZ FTSE RAFI Australia 200 ETF takes a value approach. Instead of weighting companies by their share market size, which means you automatically own more of whatever has already run hardest, QOZ weights them by measures of their actual business size, such as sales, cash flow, book value and dividends. In practice that means less exposure to the most expensive parts of the market, which is useful when valuations in areas like the banks look stretched.
And finally, for investors focused on income, the HYLD S&P Australian Shares High Yield ETF holds 50 Australian companies with high forecast dividend yields, paying distributions monthly. Importantly, it doesn’t chase yield blindly: the index screens for expected rather than past dividends and applies extra checks designed to steer clear of “dividend traps”, where a yield only looks high because the share price has fallen sharply.
